Making Homeownership More Accessible – Responsibly
Down payment assistance (DPA) programs are designed to help qualified buyers bridge the gap between savings and homeownership. When used correctly, these programs can provide meaningful access to the market without compromising long-term financial stability.
At The Loan Firm, down payment assistance is never treated as a shortcut. It’s a strategic tool – evaluated carefully to ensure it aligns with a borrower’s income, goals, and future plans.
What Is Down Payment Assistance?
Down payment assistance programs offer eligible buyers financial support toward their required down payment and, in some cases, closing costs. Assistance may come in the form of grants, forgivable loans, deferred-payment second mortgages, or low-interest subordinate liens.
Each program has specific guidelines tied to income limits, property location, loan type, and occupancy requirements. Understanding these details is essential before moving forward.
⸻
Who Down Payment Assistance May Benefit
First-Time Homebuyers
Buyers who have stable income but limited upfront savings may use DPA to enter the market sooner while preserving emergency reserves.
Moderate-Income Borrowers
Many programs are designed for households earning within specific income thresholds who may otherwise struggle to accumulate a full down payment.
Buyers Prioritizing Cash Reserves
Some clients intentionally preserve liquidity for moving costs, repairs, or life transitions while using assistance strategically.
Common Misconceptions About DPA
• Down payment assistance is not free money in every case
• Eligibility varies by location and loan program
• Assistance may impact interest rates or future resale
• Not all sellers accept offers using certain programs
Clarity upfront prevents surprises later.
⸻
When Down Payment Assistance May Not Be Appropriate
• Down payment assistance is not the right fit for every buyer. It may be less suitable when:
• Income exceeds program limits
• Competitive markets favor stronger conventional offers
• Long-term equity growth is a top priority
• Program restrictions conflict with future plans
In these cases, alternative strategies may offer better outcomes.
⸻
Our Approach to Down Payment Assistance
I don’t match clients to programs blindly. I evaluate:
• Eligibility and long-term impact
• Repayment structure and future obligations
• How assistance affects purchasing power
• Whether the program supports – not hinders – financial growth
The goal isn’t just to get you into a home.
It’s to ensure the decision still makes sense years from now.
Let’s Talk Strategy
Down payment assistance can open doors – but only when used with intention. If you’re exploring your options, we’ll walk through eligibility, trade-offs, and alternatives together so your path to homeownership is built on clarity, not pressure.
Important notes on Florida Hometown Heroes Program
The Florida Hometown Heroes Program is often misunderstood as “free money.”
It is not.
While the program provides meaningful upfront assistance, it is structured as a deferred second mortgage, not a grant.
This means:
• The assistance does not require monthly payments
• Interest does not accrue monthly
• But it must be repaid when certain events occur
⸻
When Repayment Is Triggered
The Hometown Heroes assistance becomes due and payable if the borrower:
• Refinances the first mortgage
• Sells the property
• Transfers ownership, including through a quit claim deed
• Obtains a HELOC or Home Equity Loan that requires payoff of subordinate liens
In short: any transaction that alters title or financing structure can trigger repayment.
⸻
Why This Matters Strategically
Down payment assistance can be an excellent entry point into homeownership – but it should be used with full awareness of how it affects future flexibility.
Borrowers planning to:
• Refinance in the near or mid-term
• Leverage equity through a HELOC or second lien
• Transfer ownership interests
• Restructure debt later
…should understand that the assistance behaves like a silent second mortgage, not free equity.
⸻
Our Role in This Process
My responsibility isn’t just to help you qualify – it’s to help you plan ahead.
Before recommending the Florida Hometown Heroes Program, I review:
• Your anticipated time horizon in the home
• Likelihood of refinancing or equity access
• Long-term financial and ownership goals
That way, the program supports your future – not limits it.
Down Payment Assistance as a Second Mortgage
What This Means
Some down payment assistance programs — including MMAP and certain lender-offered DPA programs — are structured as a second mortgage, not a grant.
This second mortgage is typically recorded against the property and may be:
• Deferred (no monthly payment)
• Low or zero interest
• Repayable upon specific events
While these programs can reduce the upfront cash required to buy a home, they still represent real debt secured by the property.
How Second-Mortgage DPA Works
In most cases, second-mortgage DPA must be repaid if one of the following occurs:
• You refinance the primary mortgage
• You sell the property
• You take out a HELOC or Home Equity Loan
• You transfer title (including quit claim deeds in many cases)
The assistance does not disappear — it simply sits quietly behind the first mortgage until one of these trigger events occurs.
Why This Matters Strategically
Down payment assistance can be an excellent tool when used intentionally, but it can also limit future flexibility if not fully understood.
Borrowers should consider:
• How long they plan to stay in the home
• Whether refinancing is likely in the future
• Long-term equity and leverage goals
• Whether tying up future equity aligns with their financial strategy
This is why DPA decisions shouldn’t be made in isolation — they should be evaluated alongside refinance plans, equity strategies, and long-term ownership goals.
The Loan Firm Approach
At The Loan Firm, down payment assistance is never presented as “free money.”
I help borrowers:
• Understand whether assistance is a grant or a second mortgage
• Evaluate the long-term impact on equity and refinancing options
• Compare DPA programs against alternative structures when appropriate
• Choose solutions that support both homeownership today and flexibility tomorrow
🔱Down payment assistance is not free money — it’s a financing tool with long-term implications.🔱
🔱Program structures, repayment terms, eligibility requirements and available funds vary by program and are subject to change.🔱
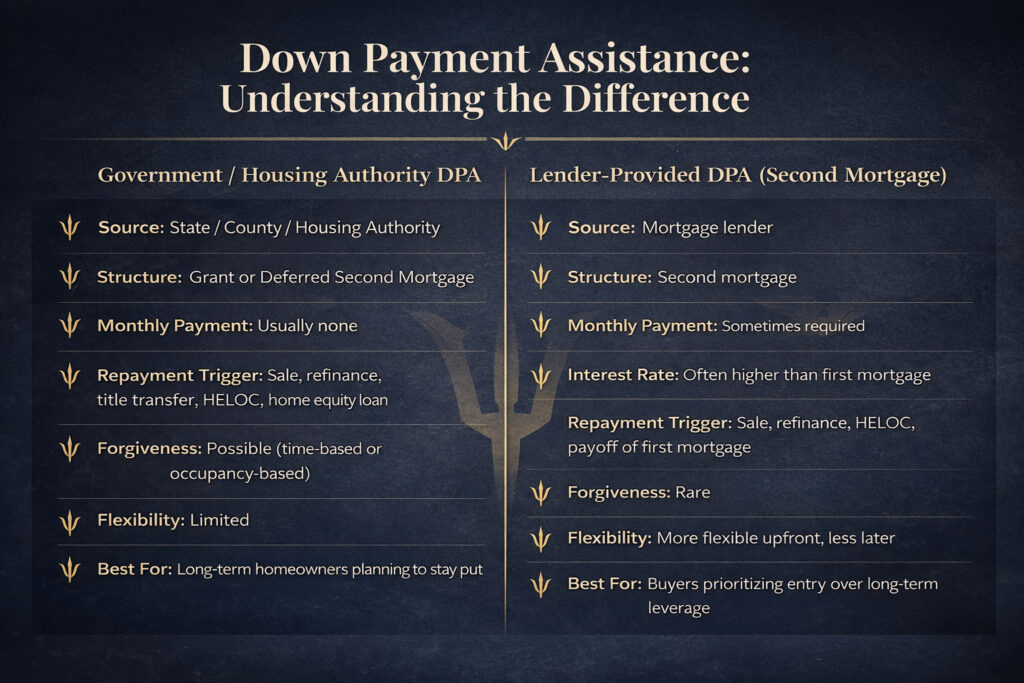
Comparison between Down Payment Assistance and Second Mortgage Down Payment Assistance
FAQs
Q: Is down payment assistance free money?
🔱No. While some programs are structured as grants, many down payment assistance programs are deferred loans or second mortgages that must be repaid under certain conditions. Repayment is often triggered by refinancing, selling the home, or paying off the first mortgage.
Q: What happens to down payment assistance if I refinance later?
🔱In most cases, the assistance balance becomes due and payable at refinance. This includes programs such as Florida Hometown Heroes and many state or county housing authority programs. The repayment amount must be factored into future equity and refinance planning.
Q: Can I use a HELOC or home equity loan if I received down payment assistance?
🔱It depends on the program. Many DPA programs restrict additional financing, including HELOCs or home equity loans, without prior approval. Some prohibit them entirely until the assistance is repaid. This is why understanding long-term flexibility matters before choosing a program.
Q: What is the difference between government DPA and lender-provided DPA?
🔱Government or housing authority DPA is typically income-restricted and may include resale or refinance conditions.
Lender-provided DPA is usually structured as a true second mortgage, often with defined repayment terms, and may offer more flexibility depending on the loan structure.
Q: Does down payment assistance affect how much equity I build?
🔱Yes. Because many programs are structured as second liens, they reduce usable equity until repaid. This can impact future refinancing, cash-out options, or property transfers.
Q: What happens if I sell my home?
I🔱Most down payment assistance programs require full repayment at sale. Some programs prorate forgiveness over time, while others require repayment regardless of how long you owned the home.
Q: Can down payment assistance be used more than once?
🔱Generally, no. Most programs are one-time use and intended for first-time or first-generation buyers. Eligibility rules vary by program and location.
Q: How do I know which down payment assistance program is right for me?
🔱There is no one-size-fits-all answer. The right program depends on your income, future plans, refinance goals, equity strategy, and long-term financial flexibility. Assistance should be evaluated as part of a broader mortgage strategy — not in isolation.
Down Payment Assistance Programs
Below are official government and housing authority resources. Availability and funding change frequently.
Program availability, funding limits, income caps, and repayment terms vary by location and are subject to change.
Florida Statewide Programs
• Florida Housing Finance Corporation (FHFC) : Official state housing finance agency and down payment assistance resource. Florida Housing Finance Corporation (State DPA & Programs)
• Florida Hometown Heroes Program : State workforce homebuyer down payment & closing cost assistance. Florida Hometown Heroes Housing Program (DPA Details)
• State-approved lender DPA options : Homebuyer Down Payment Assistance Programs Overview – FHFC’s overview of DPA options like FL Assist. Florida Housing Homebuyer Programs (FL Assist, etc.)
⸻
Miami-Dade County Down Payment Assistance
• Miami-Dade County Public Housing & Community Development : County program providing interest-free loans up to $35,000 for eligible buyers. Miami‑Dade Homebuyer Down Payment Assistance Program
• Miami-Dade Affordable Homeownership Program / Homebuyer Resources : Additional county homeownership assistance resources. Miami‑Dade Affordable Homeownership & DPA Resources
• Miami-Dade Housing Finance Authority (HFA) : Offers listed down payment assistance with mortgage combos. Housing Finance Authority of Miami‑Dade (HFA) Programs
⸻
Broward County Down Payment Assistance
• Broward County Housing Finance & Community Development : Broward County government’s homebuyer purchase assistance details. Broward County Homebuyer Purchase Assistance Program
🔱Note: Some cities in Broward, like Margate, also have local purchase assistance – you can optionally add those as submenu links.
⸻
Monroe County Down Payment Assistance
• Monroe County Housing Authority programs : Contact info and county DPA resources. Monroe County Housing Authority Homebuyer Assistance Contact Info
🔱Monroe doesn’t have a big centralized online DPA page, but this HUD directory lists the housing and assistance department for Monroe that manages programs.
⸻
Important Note
🔱 Program rules, eligibility requirements, repayment terms, and funding availability can change without notice. Always confirm current guidelines before applying. 🔱